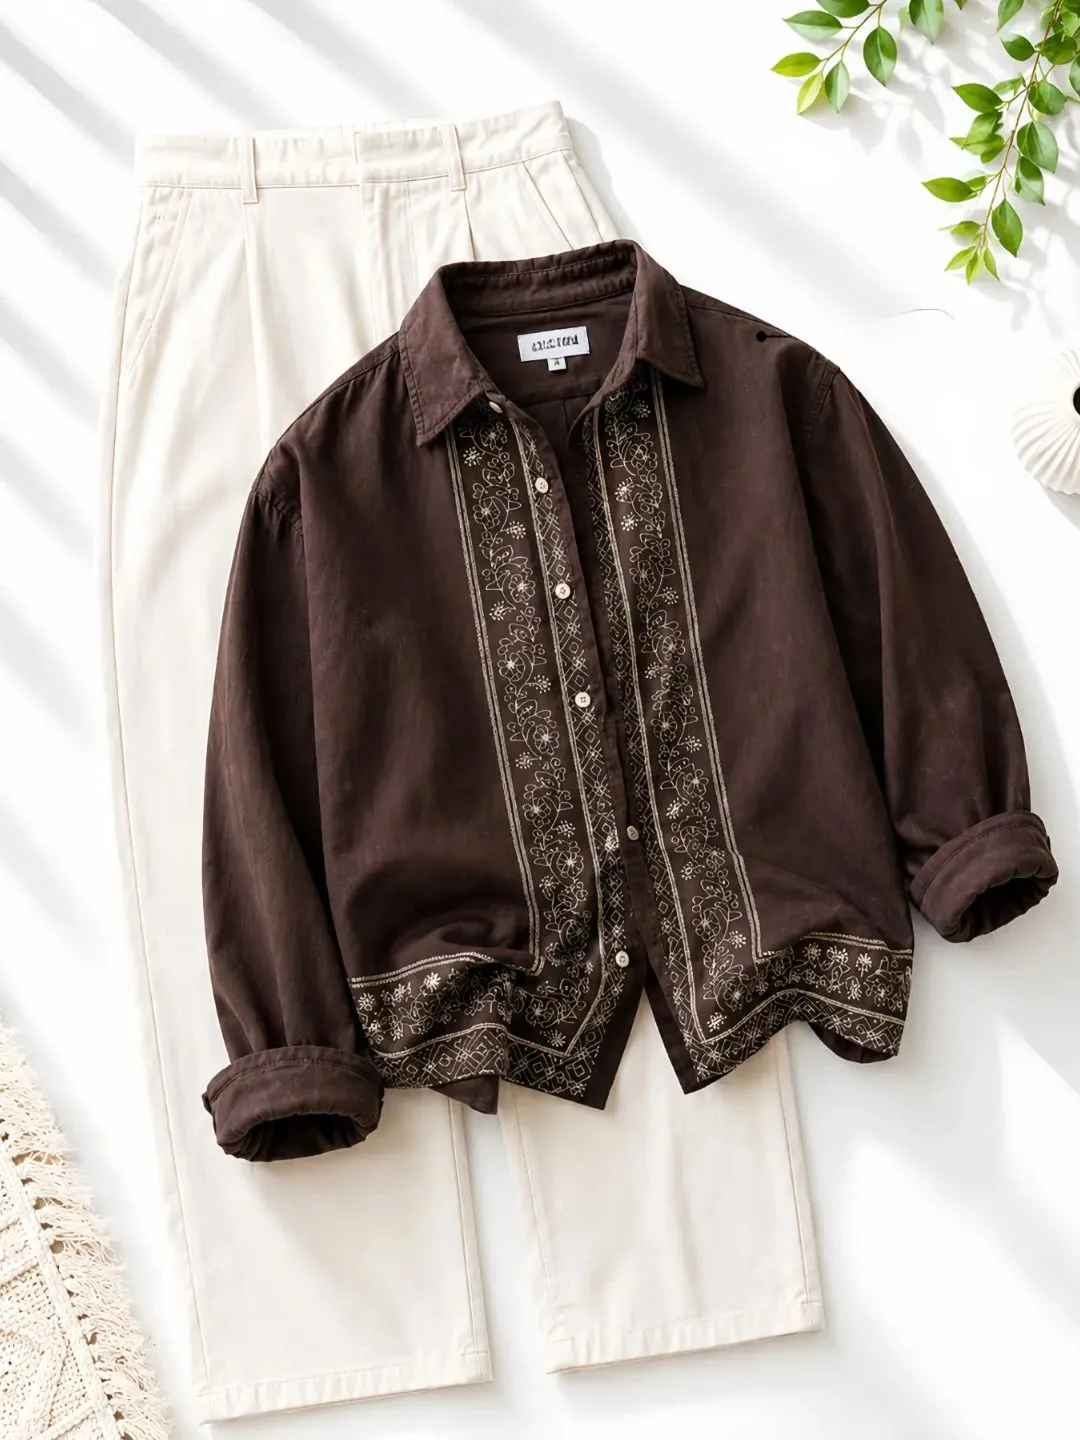
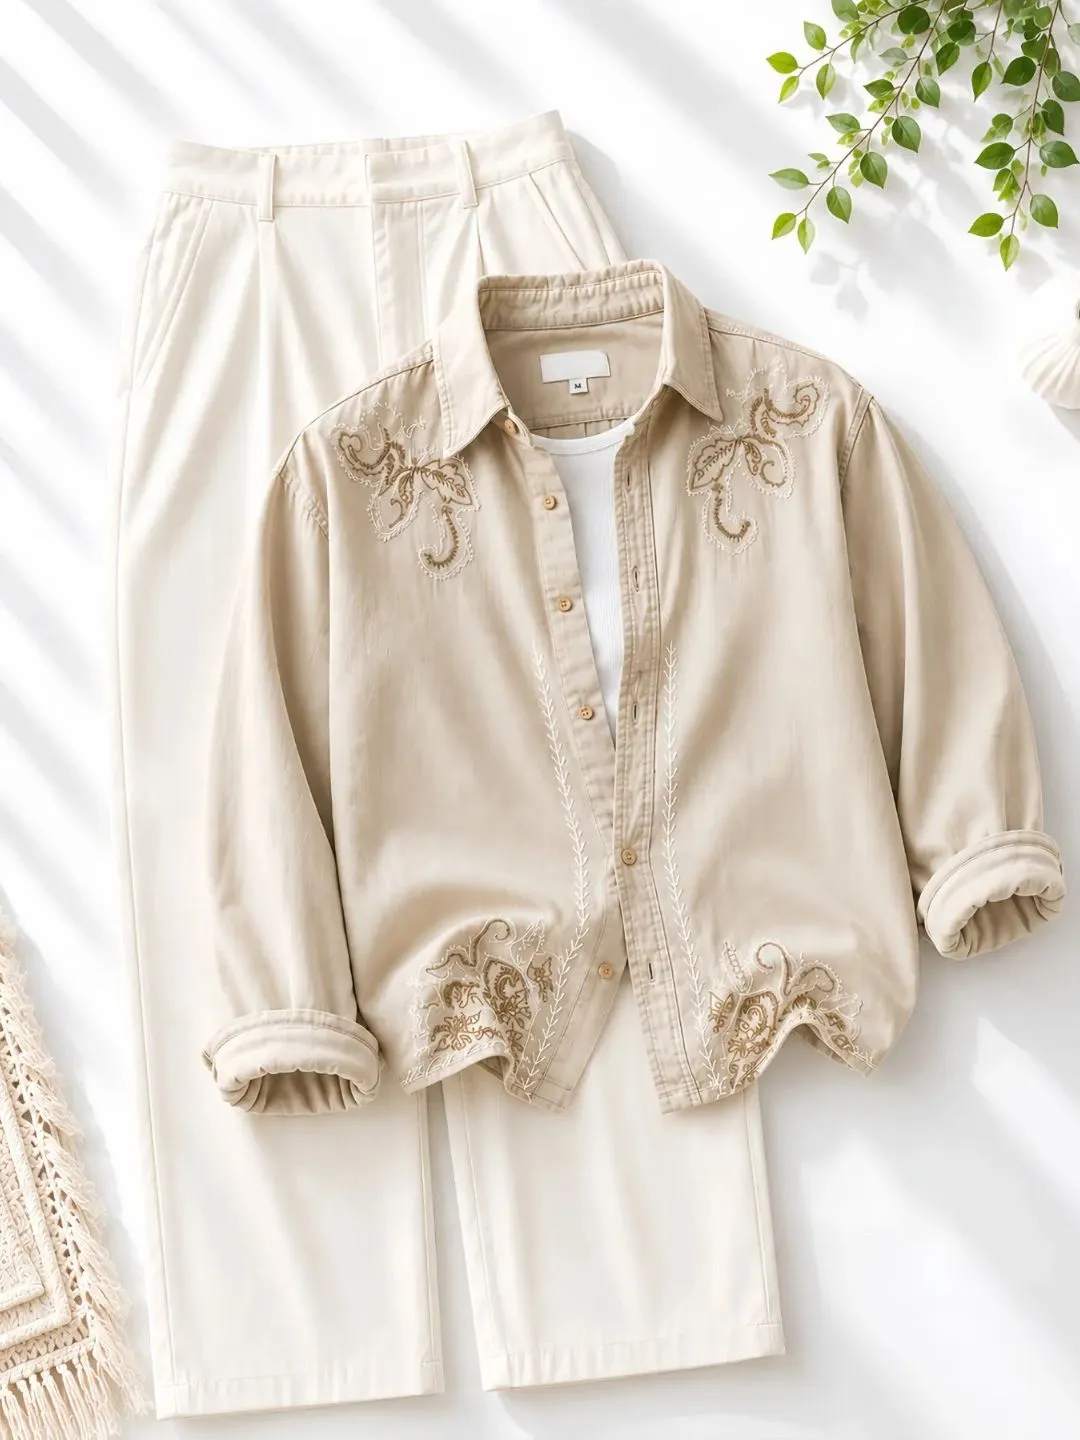
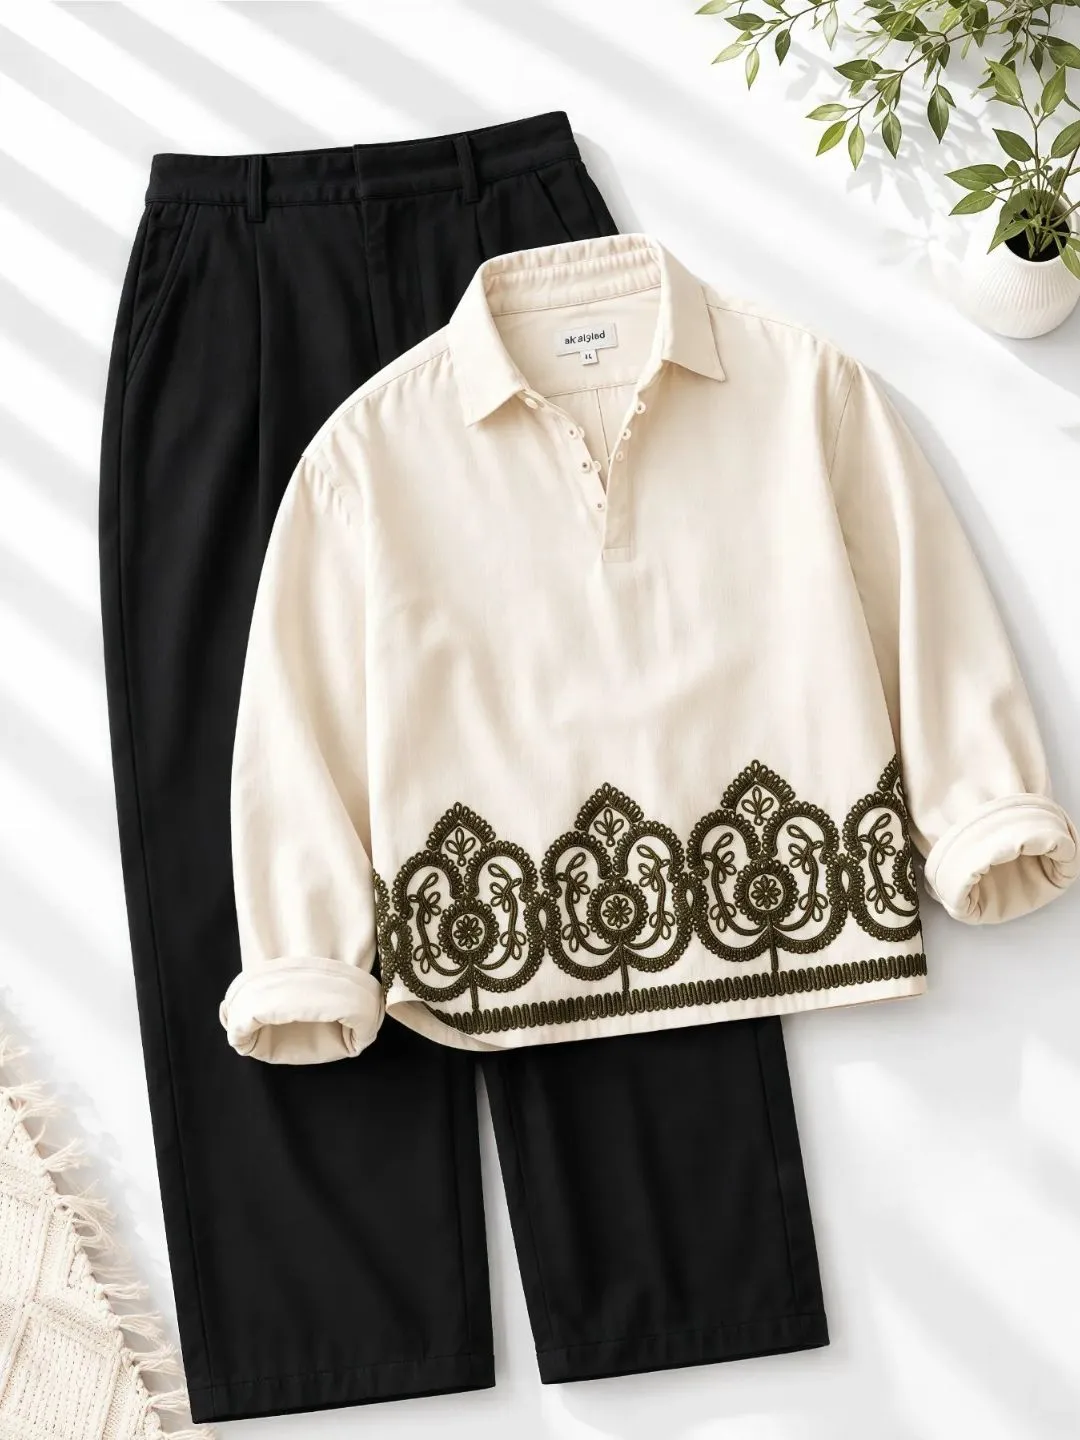
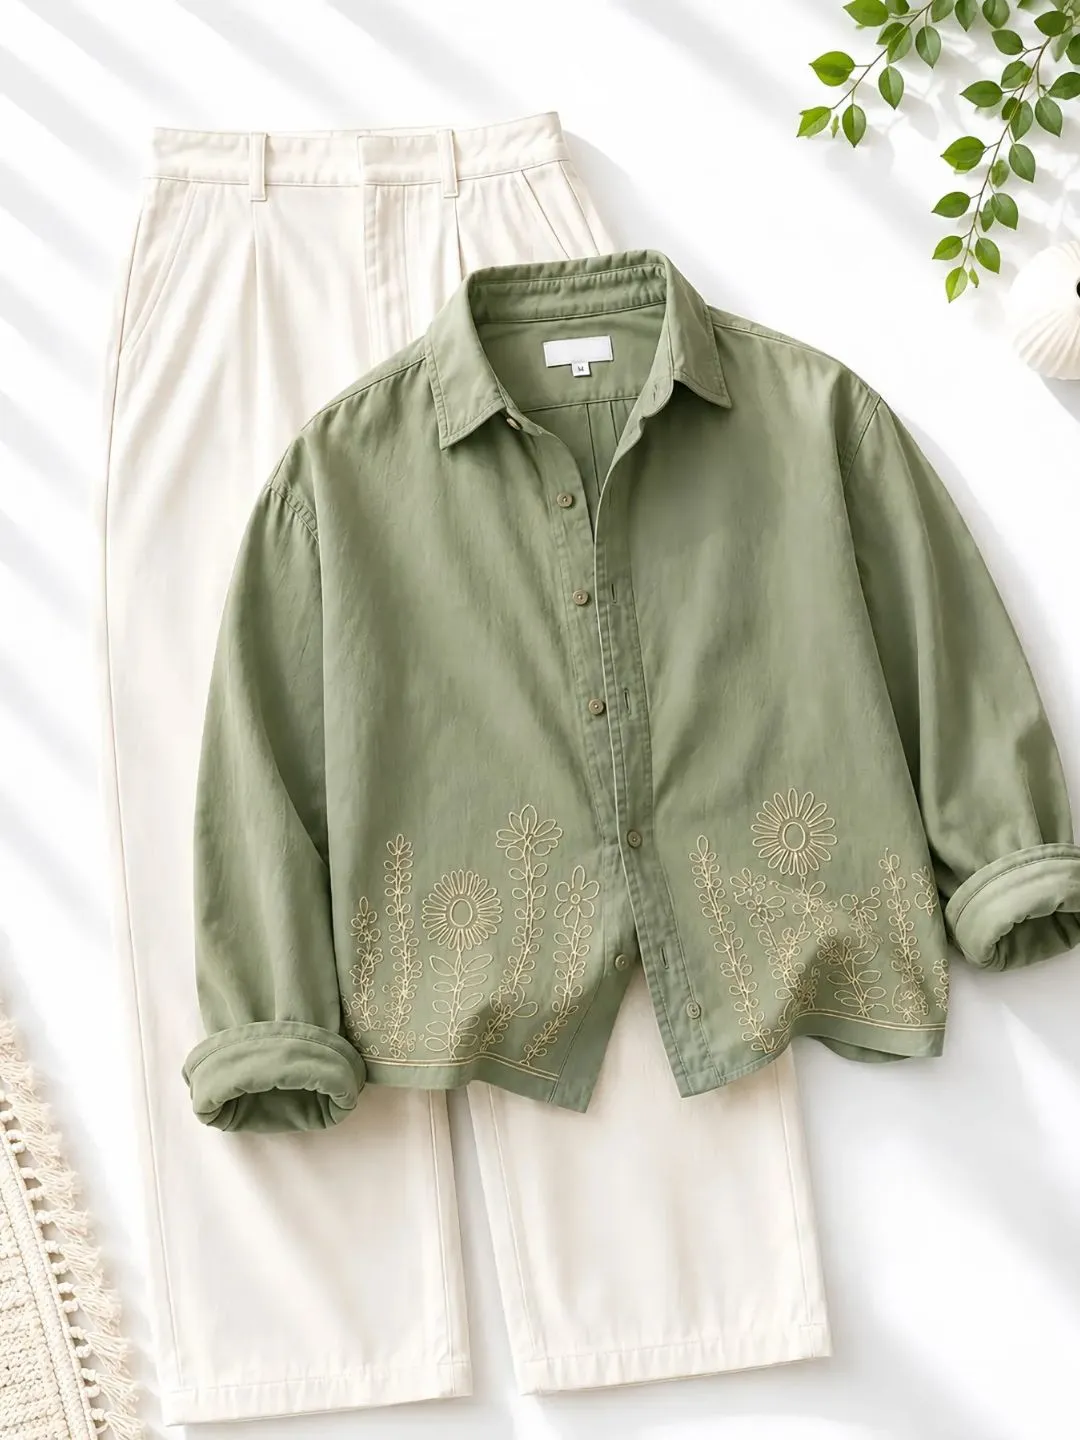
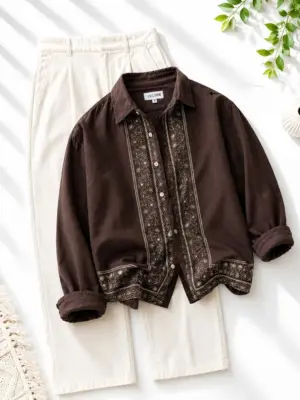
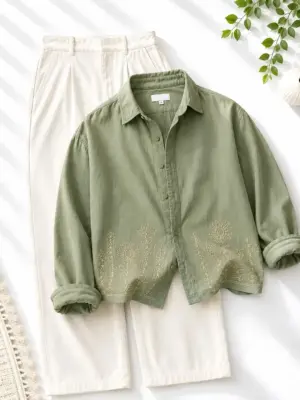
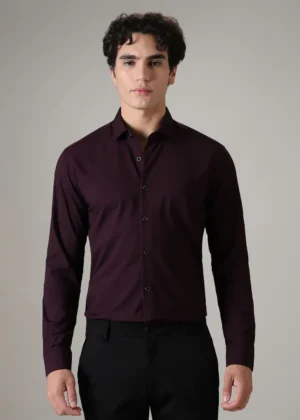
Brown Long-Sleeve Shirt with Embroidery and Off-White Trousers Combo
Original price was: ₹799.00.₹119.00Current price is: ₹119.00.
Cash on Delivery Available | Limited Stock | Trending Style
Product Details
- Product Type: Shirt & Trousers Combo
- Shirt Color: Rich Brown with Contrast Placket Embroidery
- Trousers Color: Off-White
- Sleeves: Full Sleeves
- Fit Type: Relaxed Modern Fit
- Collar Type: Classic Spread Collar
- Fabric: Premium Cotton Linen Blend
- Pattern: Solid Body with Intricate Placket and Hem Embroidery
- Style: Bohemian Casual / Smart Chic / Artisan Modern
- Occasion: Daily Wear, Travel, Casual Outings, Weekend Gatherings
Upgrade your casual wardrobe rotation with this exceptionally stylish and meticulously coordinated two-piece ensemble, featuring a rich brown long-sleeve button-down shirt adorned with intricate floral embroidery along the front placket and hemline, paired seamlessly with relaxed off-white trousers. Crafted from a soft, breathable, and high-quality cotton-linen blend fabric, this complete outfit guarantees supreme all-day comfort without ever compromising on a sharp, artisanal silhouette.
Riding around without proper two wheeler insurance feels harmless right up until the day it isn’t, and by then it’s way too late to fix the mistake. Third-party cover is legally mandatory in India, but sticking to just the minimum required policy is one of those decisions that looks smart on paper and terrible in practice. It only pays for damage you cause to someone else’s vehicle or property, not a single rupee for your own bike if it’s stolen, damaged in an accident, or wrecked in a flood.
A comprehensive two wheeler insurance policy costs a bit more, but it covers your own vehicle too, and that difference matters a lot more than people realize until they’re staring at a repair bill for a cracked fairing or a burnt-out engine after monsoon flooding. If you’ve taken a loan to buy the bike, most lenders will insist on comprehensive cover anyway, so you might as well understand what you’re actually paying for.
The add-ons are where the real value hides. Zero depreciation cover means the insurer pays for parts replacement without deducting for wear and tear, which matters a lot on newer bikes where a single claim without this add-on can leave you paying half the repair cost yourself. Engine protection cover is another one worth considering if you live somewhere that floods during monsoon season, since water damage to the engine is usually one of the costliest repairs a two-wheeler owner faces.
Your no claim bonus is basically a reward for not filing claims, and it can knock a solid chunk off your renewal premium every claim-free year, sometimes stacking up to 50% off over time. The trap a lot of riders fall into is filing a claim for something minor, like a small scratch, and losing that bonus over a repair that would’ve cost less out of pocket anyway. Before you file any claim, do the math on whether the repair cost is actually higher than what you’d lose in bonus and premium hike.
Buying online has made comparing insurers painfully easy, so there’s no real excuse for renewing blindly with whichever company sends the first reminder text. Check the cashless garage network near you, read a few claim settlement reviews, and actually compare IDV, the Insured Declared Value, across insurers, because a lowball IDV means a lowball payout if your bike is ever declared a total loss.
| Size | 3XL, 4XL, L, M, S, XL, XS, XXL |
|---|
Leaving Comments
Leave a Comment
Related products






Reviews
There are no reviews yet.