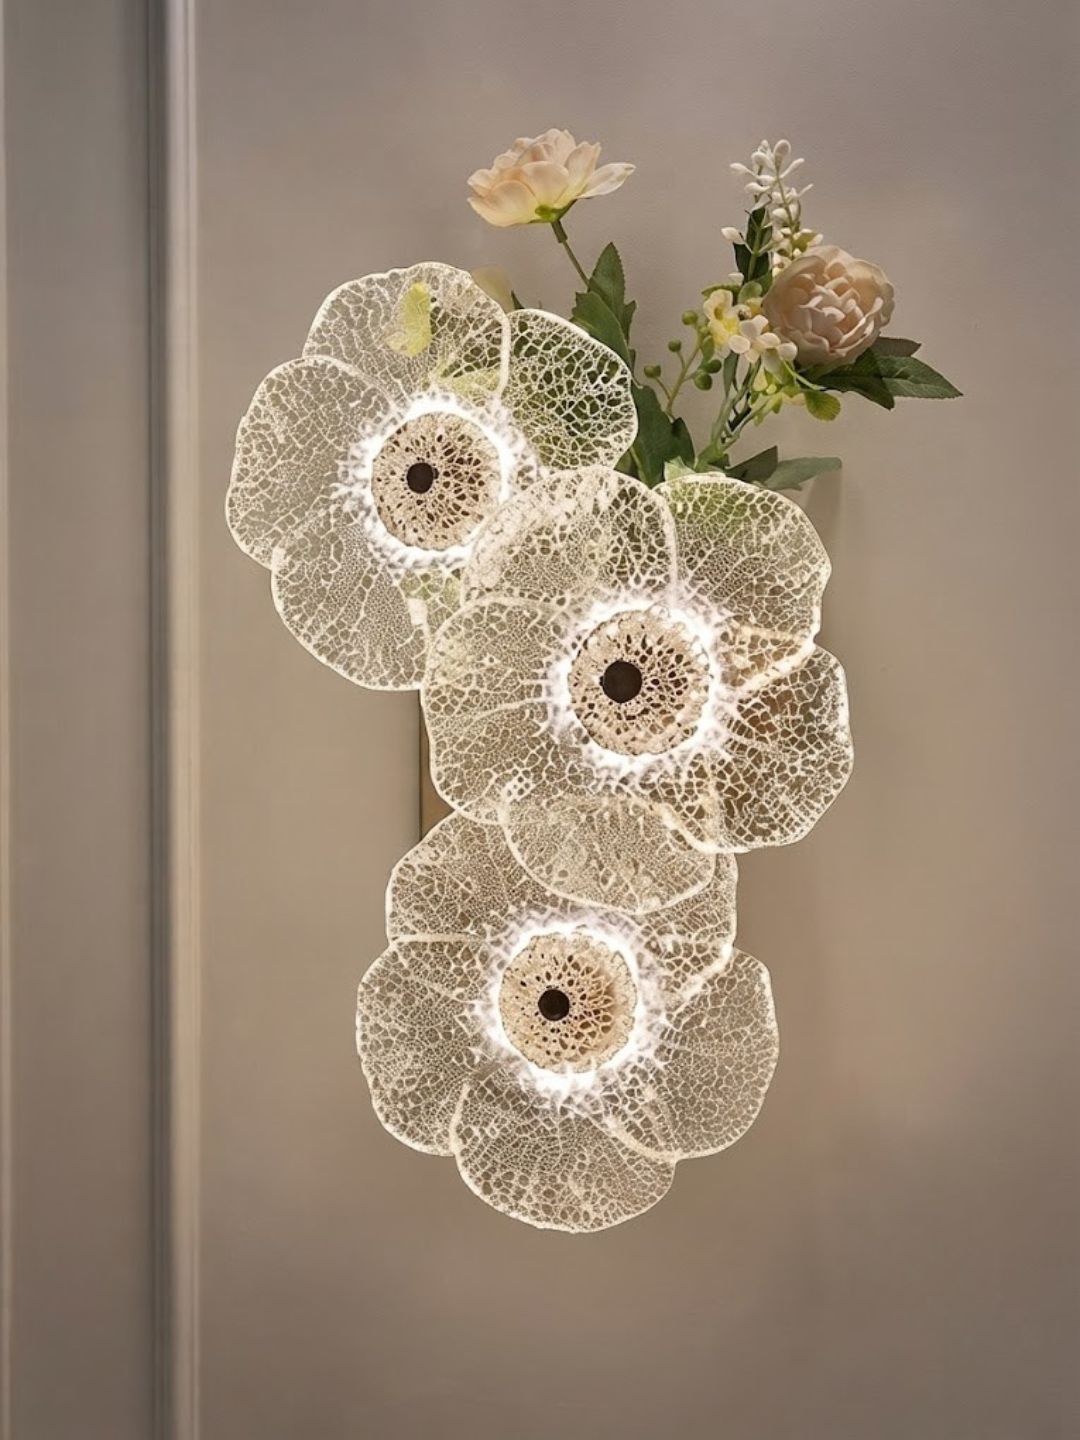
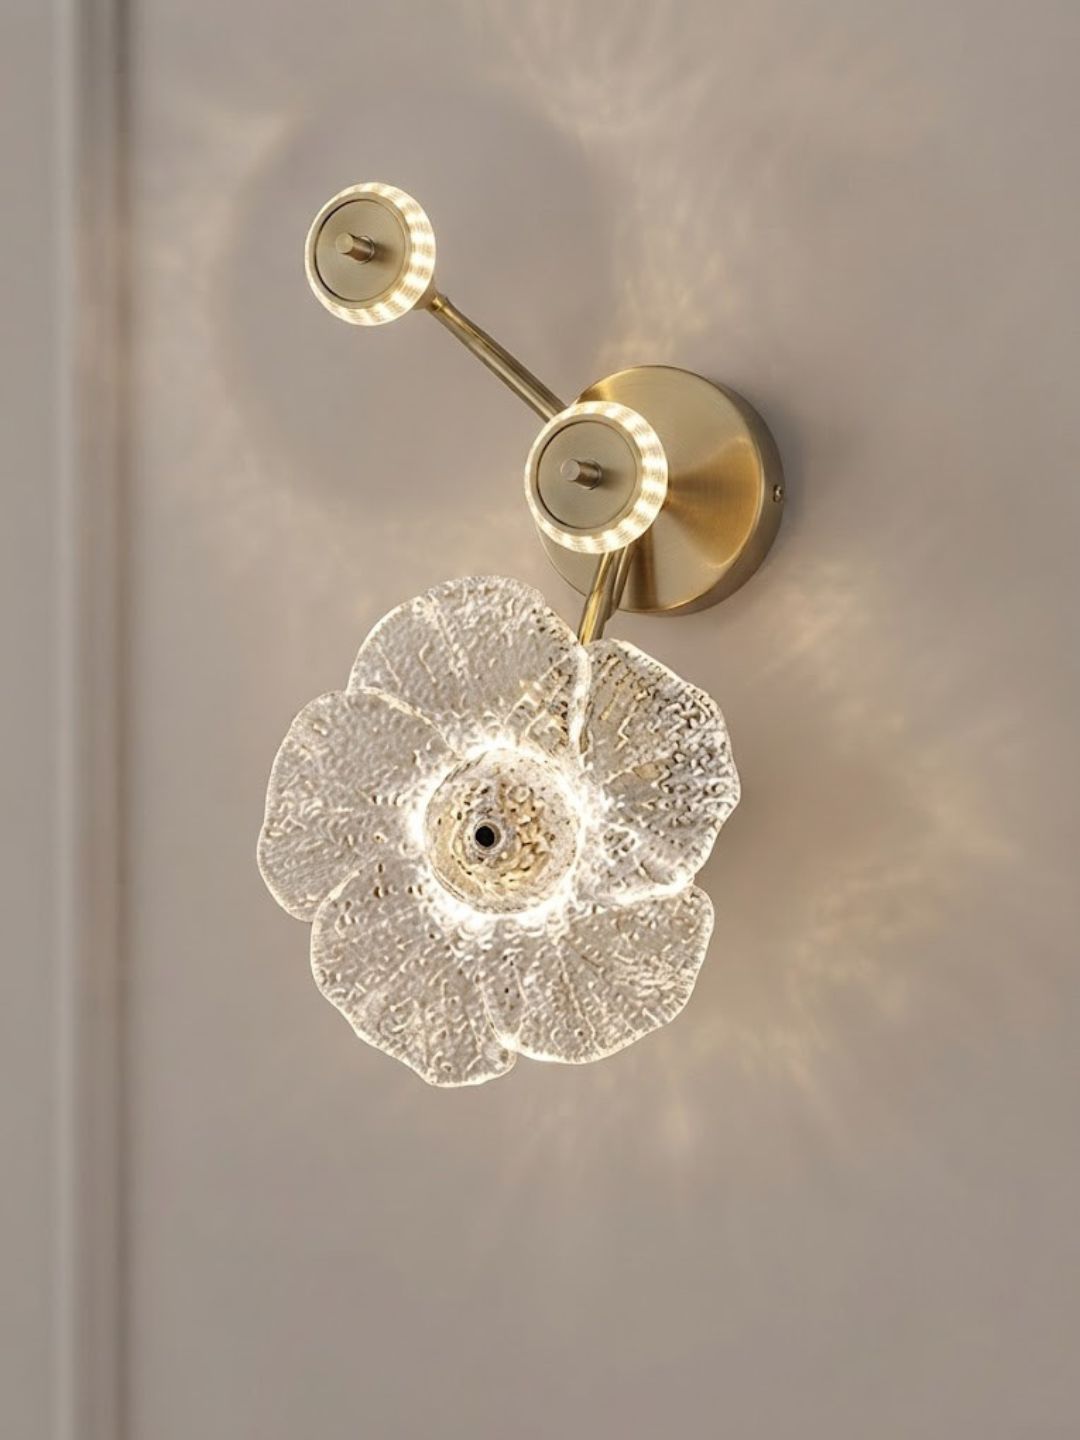
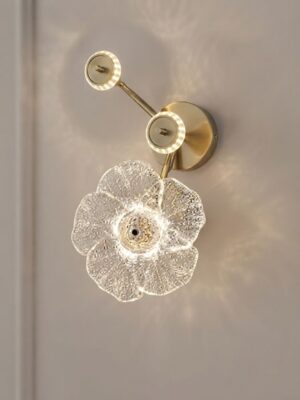
Acrylic Floral Wall Light & Decorative Accent Panel
₹99.00
Cash on Delivery Available | Limited Stock | Trending Style
Product Details:
- Product Name: Transparent Floral Acrylic Wall-Mounted Decorative Light Panel
- Product Type: Home Decor / Wall Accent Lighting
- Color: Clear Textured Acrylic with Warm LED Center Glow
- Material: High-Quality Textured Acrylic and LED Components
- Special Features: Elegant flower petal design, soft ambient illumination, peel-and-stick or easy wall-mounting setup, stackable modular arrangement
- Usage: Enhancing living room walls, bedroom headboards, hallway entryways, and accent photo corners
- Occasion / Usage: Home Makeovers, Room Styling, Ambient Lighting, and Interior Decoration
Elevate your home aesthetics with this stunning transparent floral acrylic wall light panel. Featuring a delicate, textured flower design that catches and diffuses light beautifully, this decorative piece adds a warm, cozy ambiance to any bare wall. Whether used as a standalone statement piece or arranged in a cluster to create a glowing botanical wall display, it transforms your living space with minimal effort and maximum style.
Co-payment clauses are probably the biggest surprise for first-time buyers. Many senior citizen policies require you to pay a fixed percentage of every claim out of pocket, sometimes 10-20%, regardless of how large the sum insured is. It’s the insurer’s way of managing risk on an age group that statistically files more claims, but it also means your actual out-of-pocket cost during a hospitalization can be higher than expected even with a solid policy in place.
Waiting periods are the other thing to watch closely. Most conditions common in older age, like cataracts, joint replacements, or pre-existing illnesses such as diabetes and hypertension, come with a waiting period before they’re covered, sometimes stretching to two or three years. If your parents already have a pre-existing condition, buying the policy earlier rather than later reduces how long that waiting period actually delays real coverage.
Pre-policy medical checkups are usually mandatory for senior citizen health insurance, and this actually works in your favor even though it feels like a hassle. It gives you a clear picture of existing health issues, and it means the insurer can’t reject a claim later citing an undisclosed condition, since the checkup already put everything on record. Always disclose every existing condition honestly on the proposal form, because non-disclosure is one of the most common reasons claims get rejected at the worst possible time.
| Size | 3XL, 4XL, L, M, S, XL, XS, XXL |
|---|
Leaving Comments
Leave a Comment
Related products


Reviews
There are no reviews yet.