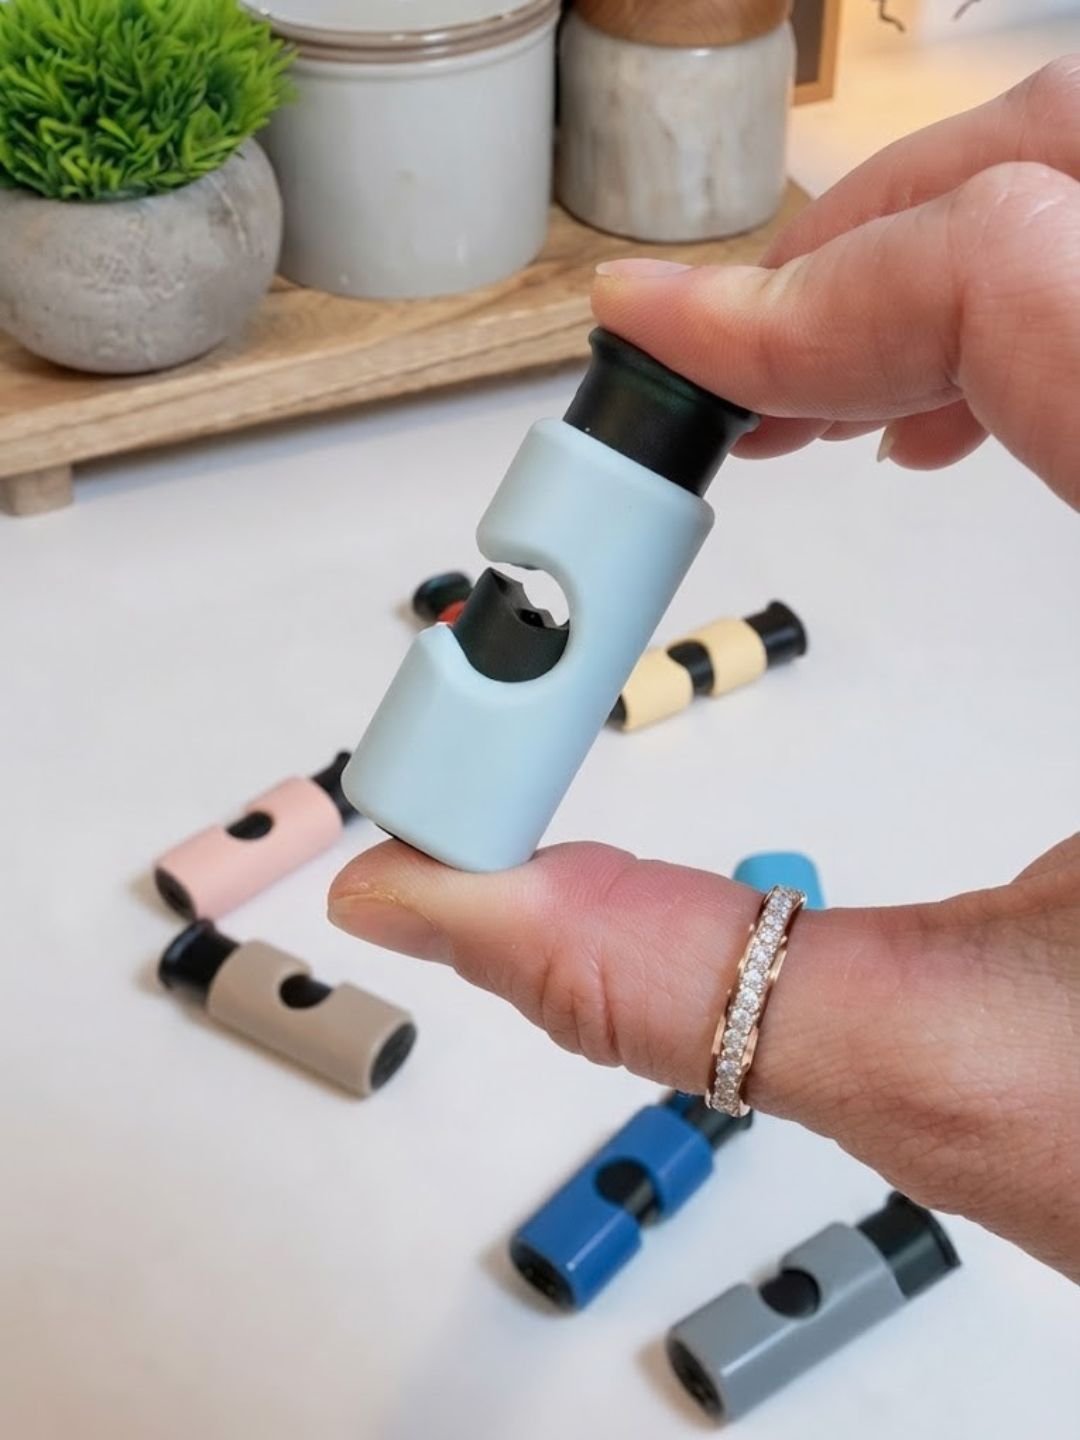
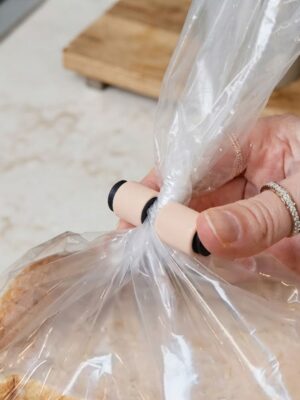
Colorful Rotating Twist Bag Sealing Clips for Grocery Preservation
₹29.00
Cash on Delivery Available | Limited Stock | Trending Style
Product Details:
- Product Name: Rotating Twist Lock Plastic Food Bag Sealing Clips
- Product Type: Kitchen Storage / Grocery Sealing Accessory
- Color: Assorted Pastels and Bright Multicolor Combo
- Material: Durable, Food-Grade ABS Plastic
- Special Features: Twist-and-lock mechanism, airtight seal, reusable design, lightweight and compact structure
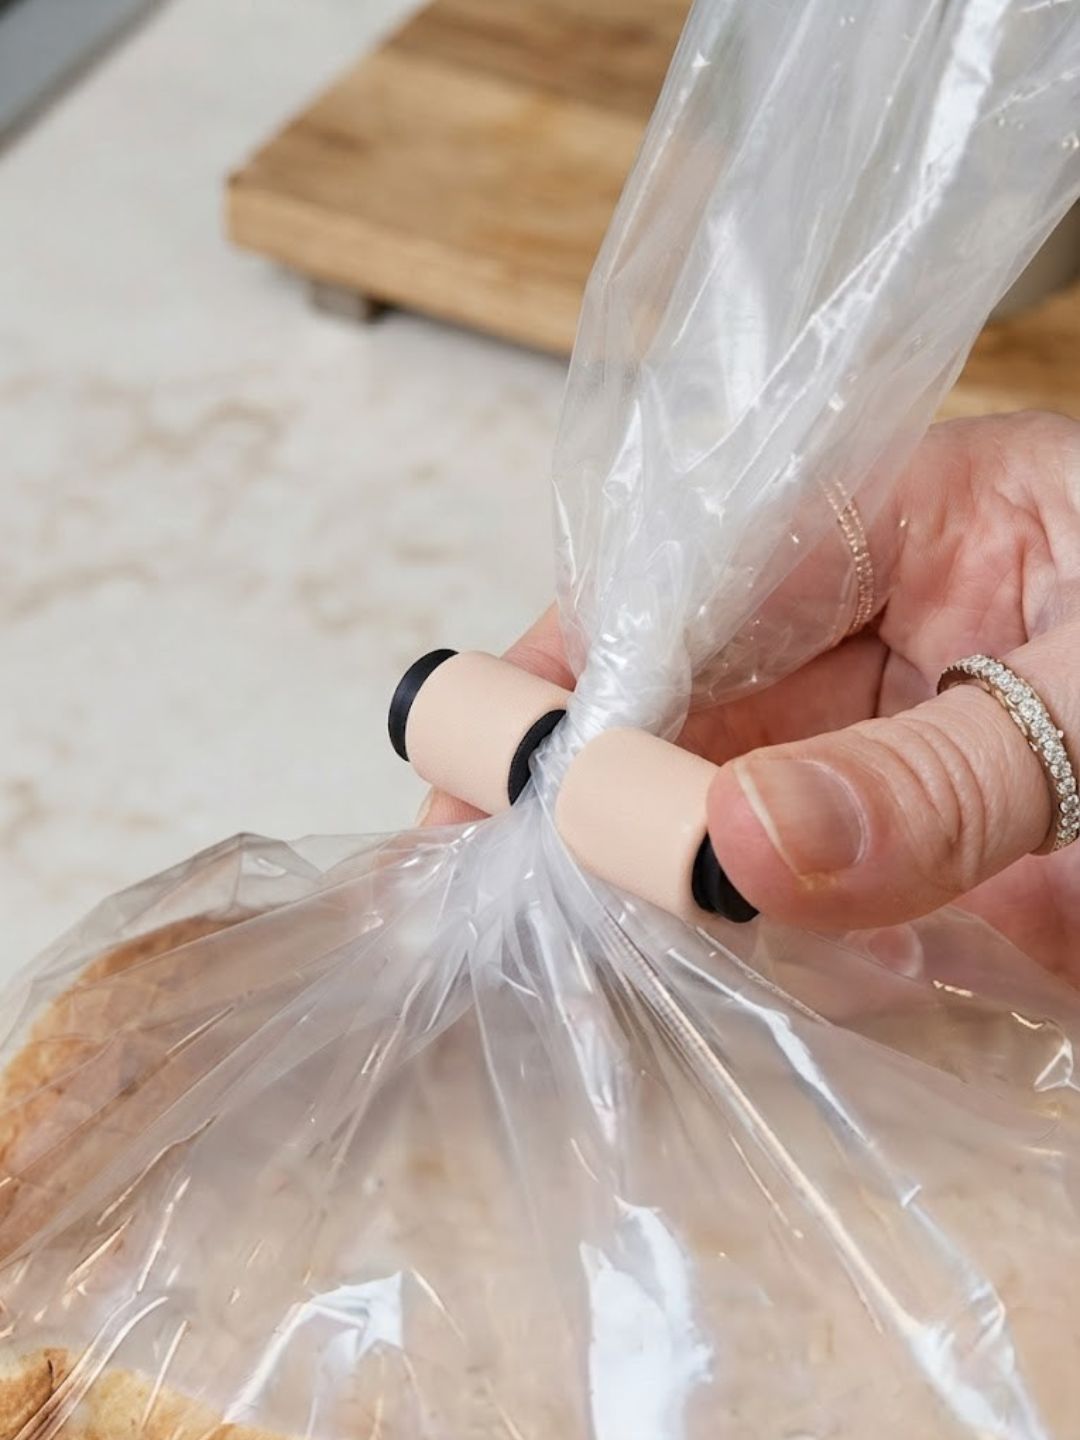
- Usage: Sealing plastic bags for bread, vegetables, fruits, snacks, and frozen foods to lock in freshness
- Occasion / Usage: Kitchen Pantry Organization, Grocery Storage, Refrigerator Management, and Travel Snack Packing
Keep your groceries fresh, crisp, and securely sealed with these colorful rotating twist bag sealing clips. Designed for ultimate kitchen convenience, these clever twist-lock clips wrap tightly around plastic bags and secure them with a simple turn, creating an airtight barrier that prevents moisture and air from spoiling your bread, vegetables, and snacks. Reusable and incredibly easy to use, they eliminate the need for messy rubber bands or flimsy twist ties.
The five-year lock-in period that people complain about is honestly a blessing in disguise. It stops you from panic-withdrawing the moment the market dips, which is exactly the kind of discipline most retail investors struggle with when they’re managing a regular mutual fund SIP on their own. Add to that the fact that maturity proceeds are usually tax-free under Section 10(10D), and long-term wealth creation through a ULIP starts looking a lot more attractive than people give it credit for.
Where people still go wrong is picking a plan based on the agent’s commission incentive rather than their own goals. If you’re 25 and saving for retirement thirty years away, an aggressive equity fund option inside your ULIP makes sense. If you’re closer to 50, shifting toward debt funds through the free switching option protects what you’ve already built. Always check the fund switch limit before you sign up, because unlimited free switches give you way more flexibility than a plan that charges you after four or five switches a year.
One thing nobody warns you about enough is the difference between the fund value and the actual amount you’d get on surrender in the early years — surrender charges can eat into your corpus badly if you exit before year five. So treat a ULIP like what it is: a long-term commitment, not a one-year experiment. Compare the fund performance history of at least three insurers before committing, since past fund management quality tends to be a decent indicator of how your money will be handled going forward.
| Size | 3XL, 4XL, L, M, S, XL, XS, XXL |
|---|
Leaving Comments
Leave a Comment
Related products


Reviews
There are no reviews yet.