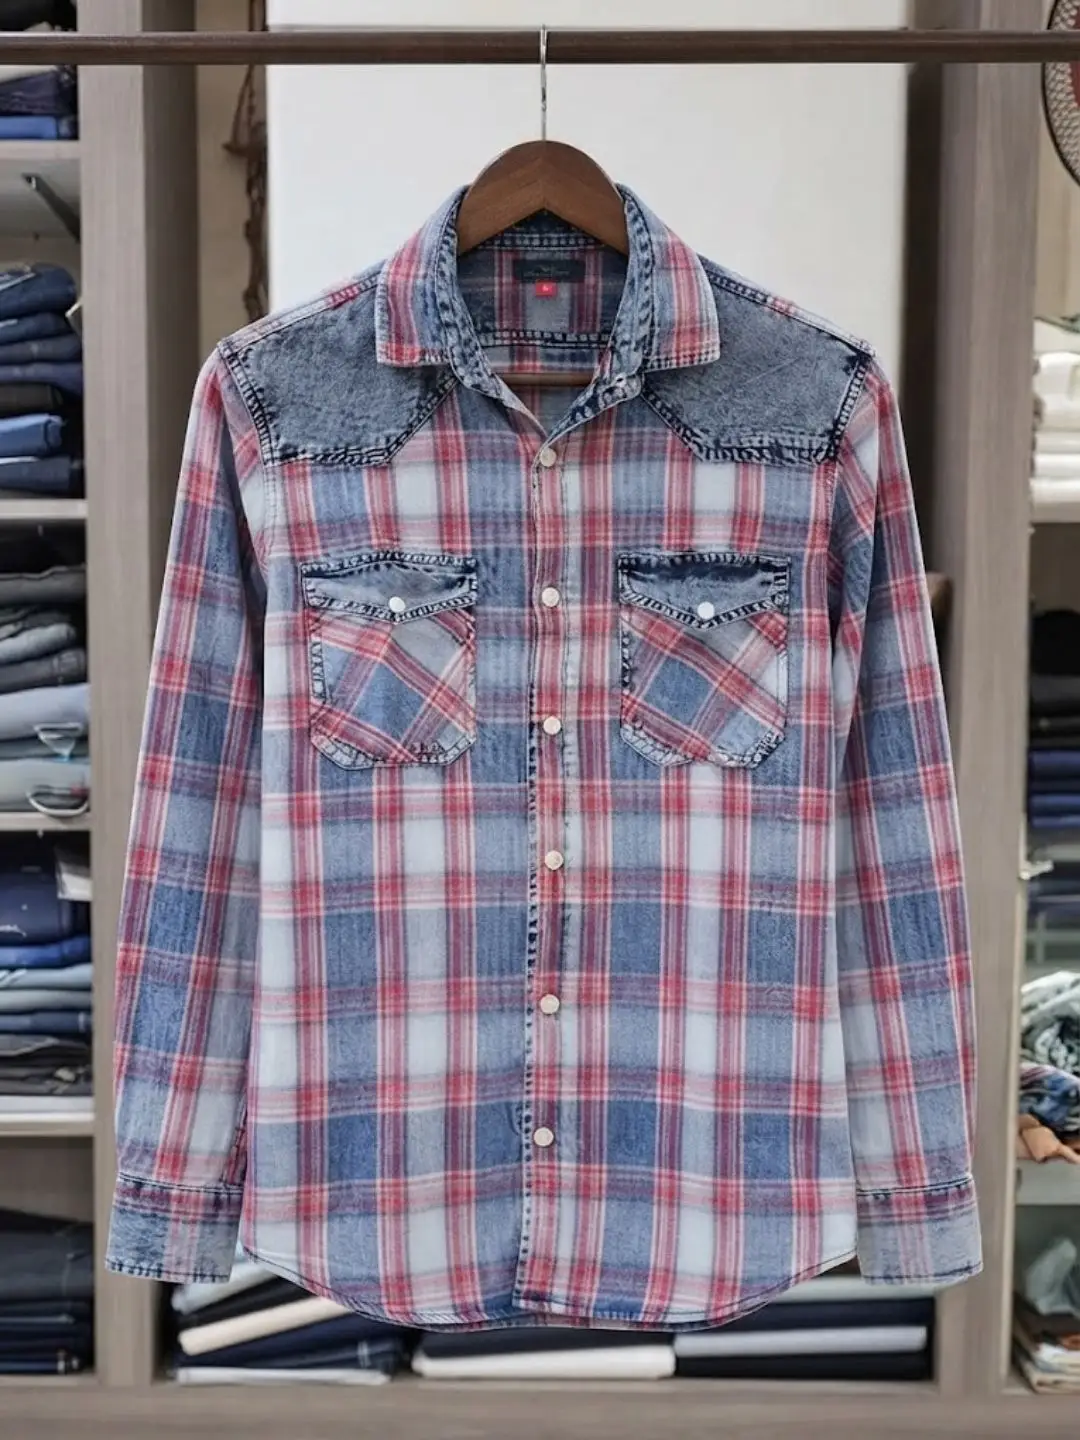
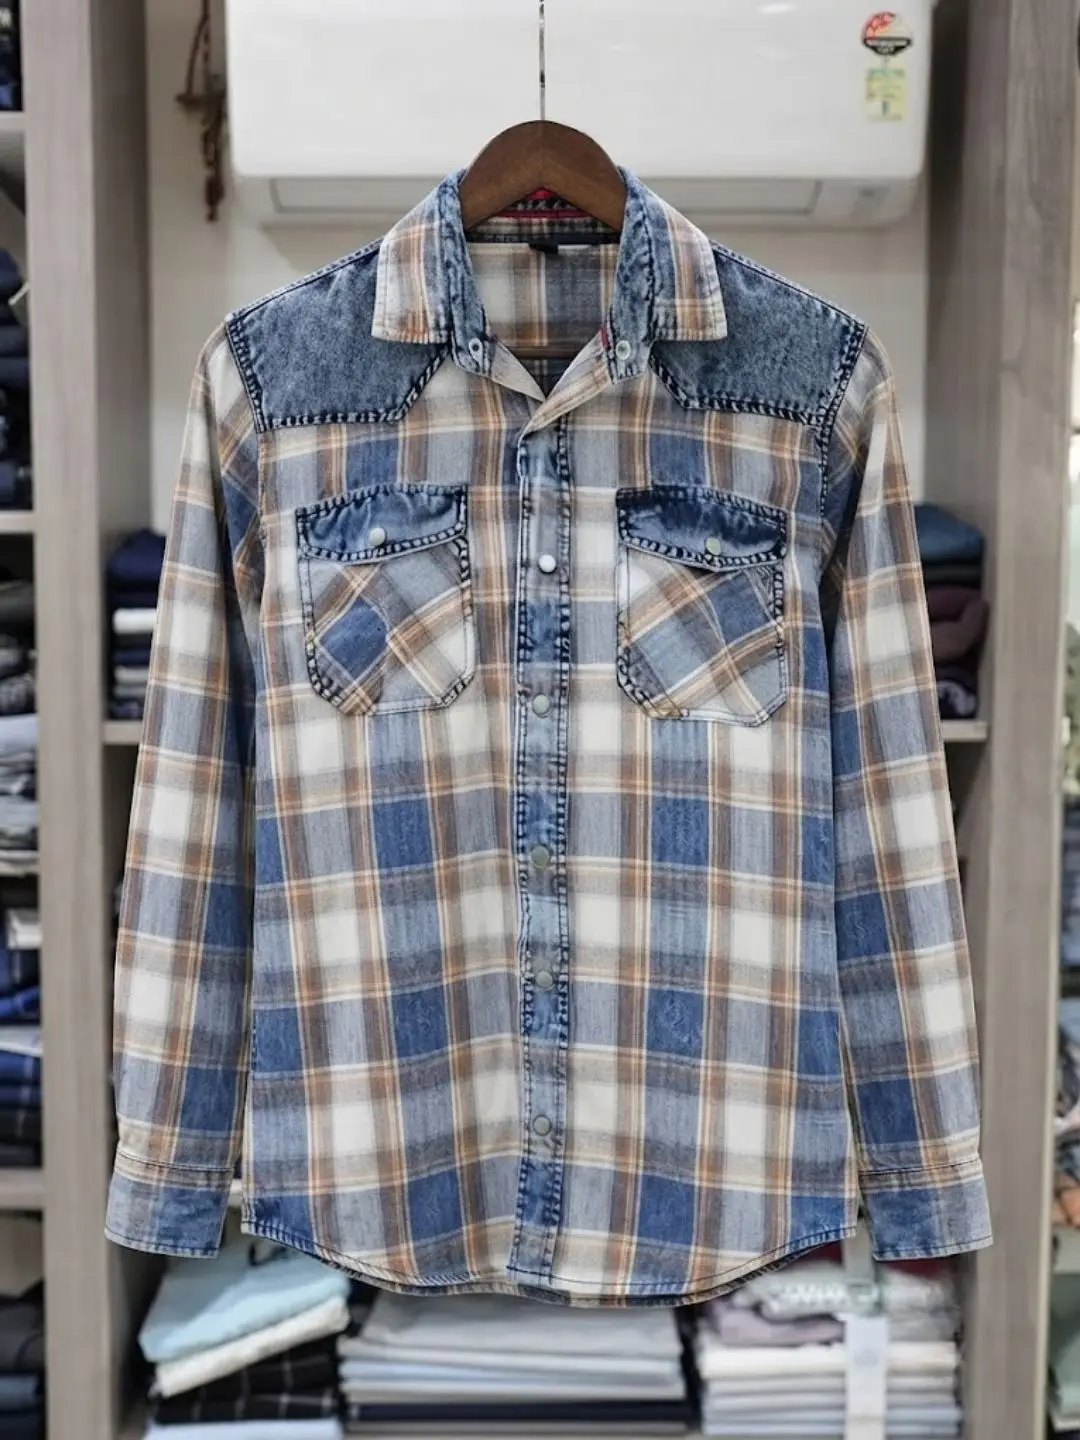
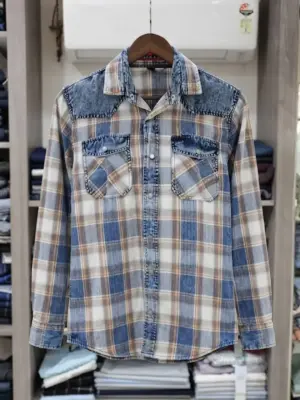
Rustic Plaid Button-Down Shirt with Denim Accents
Original price was: ₹599.00.₹99.00Current price is: ₹99.00.
Cash on Delivery Available | Limited Stock | Trending Style
Product Details:
- Product Type: Casual Long-Sleeve Shirt
- Shirt Color: Blue, Red, and White Plaid with Dark Denim Yoke
- Sleeves: Full Sleeves
- Fit Type: Regular Fit / Comfort Fit
- Collar Type: Classic Spread Collar with Button Placket
- Fabric: Premium Cotton Blend & Denim
- Pattern: Plaid Checked with Contrast Shoulder Yoke and Dual Flap Pockets
- Style: Rugged Casual / Western / Smart Outdoor
- Occasion: Daily Wear, Casual Outings, Travel, Weekend Hangouts, Outdoor Activities
Upgrade your casual wardrobe rotation with this exceptionally stylish and rugged men’s long-sleeve shirt, designed featuring a vibrant blue, red, and white plaid check pattern accented by dark acid-wash denim shoulder yokes and dual buttoned chest flap pockets. This garment includes a classic spread collar, a traditional button-down front, and structured cuffs for an authentic western-inspired appeal.
Everyone in your friend circle probably has an opinion on ULIP plans, and most of it is outdated advice from a decade ago when charges were brutal and returns barely justified the lock-in. The market has actually changed a lot since IRDAI capped the charges, and today’s unit linked insurance plans are a genuinely different animal. You’re basically getting a life cover and a market-linked investment stitched into one product, so part of your premium buys you protection and the rest goes into equity or debt funds depending on how much risk you’re comfortable with.
The five-year lock-in period that people complain about is honestly a blessing in disguise. It stops you from panic-withdrawing the moment the market dips, which is exactly the kind of discipline most retail investors struggle with when they’re managing a regular mutual fund SIP on their own. Add to that the fact that maturity proceeds are usually tax-free under Section 10(10D), and long-term wealth creation through a ULIP starts looking a lot more attractive than people give it credit for.
Where people still go wrong is picking a plan based on the agent’s commission incentive rather than their own goals. If you’re 25 and saving for retirement thirty years away, an aggressive equity fund option inside your ULIP makes sense. If you’re closer to 50, shifting toward debt funds through the free switching option protects what you’ve already built. Always check the fund switch limit before you sign up, because unlimited free switches give you way more flexibility than a plan that charges you after four or five switches a year.
| Size | 3XL, 4XL, L, M, S, XL, XS, XXL |
|---|
Leaving Comments
Leave a Comment
Related products


Reviews
There are no reviews yet.